


ICM HPQC News Flash - October 2026
Updated: 5 days ago
By Oliver Campbell │ ICM HPQC Fund │ October 2026
“Written by humans, please don’t blame the robots for our typos”

“It’s not what you said, it’s how you said it”
Welcome to the October edition of HPQC Signal, where we host Dr Hector Gonzalez, founder of SpiNNcloud for lunch; HPQC Advisory Chair Dr Bill Jeffey looks at successes and failures in scaling technologies; HPQC Principal Oliver Campbell analyses growing financial strength in the supply chain and how that can benefit portfolio companies. And finally, we dive into the most glaring logical contradictions that went mostly unnoticed in this quarter’s earnings season at Nvidia, Marvel and Broadcom.
HPQC Fund 2 is open
A reminder that HPQC Fund 2 is currently open to eligible investors. The investment thesis remains intact, with Fund 1 providing a number of useful proof points and a pipeline of opportunities emerging across the compute infrastructure stack.
If you would like to find out a bit more about what we are seeing across our Fund 1 companies, as well as the opportunities for Fund 2, book a meeting with Ollie or Matt.
Click here for the non-NDA data room.
SpiNNcloud: Data Centre Week
We had Dr Hector Gonzalez, founder of SpiNNcloud, join us for lunch in Singapore during Data Centre Week on October 1st.

The lunch was fully booked, and we are very grateful for all those who attended. We can provide takeaways (notes, not food) from the event for those interested or unable to attend the event. Suffice to say that Dr Hector did a masterful job of explaining sparse computing and its role in the future of compute. It takes a truly special mind to be able to explain something inordinately complex in such a clear way. We are very grateful to Hector Gonzalez for his time.

Click here for follow-up or if you want to be kept abreast of future events like these.
Building a better mousetrap
Every deep-tech pitch has the same chart: one dot sitting alone, far from the competition. But how often does that “better mousetrap” actually become a successful business?
HPQC’s irrepressible Advisory Board Chair, Dr Bill Jeffrey, explores this question, using Iridium and Concorde as examples of technologies that were technically impressive but ultimately struggled to translate technological advantages into sustainable commercial success.
Iridium spent billions on satellites, went bankrupt within a year, and sold for $25m. Its technology worked; terrestrial cellular technology just kept getting better. Concorde halved the Atlantic crossing, then lost most of its routes to an overland supersonic ban.
The lesson is an important one: a scaling law tells you what's physically possible, but not necessarily what's commercially viable. Herein lie three questions every deep-tech investor should ask before backing a better mousetrap.
Click here for the article and here to join the HPQC Substack “Absolutely Fabless – The Future of Compute”.
Competition, collaboration or collusion?
HPQC Principal Oliver Campbell breaks down cashflows, returns and analyses the evolving fortunes of the supply chain over the past 20 years, arguing that stronger incumbents can in fact be better for the stack overall - and potentially for HPQC investments too.
Twenty years ago, the branded OEM at the top dominated. It ran negative working capital, forced double-digit annual price cuts on suppliers, and left them with thin margins. Today, suppliers that control genuine chokepoints - including EUV lithography, leading-edge foundry, HBM, data centre power - can hold large cash balances and earn structurally higher returns, while suppliers in commoditised segments continue to fight for margin. The article draws three implications for HPQC's portfolio:
Find the chokepoint and defend it.
A company's margins depend on how narrow the physical bottleneck it controls is, not on the size of its total addressable market (TAM). Substitution should be hard because of physics, yield, IP or long qualification cycles, and ideally that difficulty should grow as the technology advances. Diraq is the example: it rents fab access from imec, and its real moat is twenty years of know-how in making CMOS-compatible spin qubits work.
Avoid commoditisation, and keep monitoring for it.
The warning signs are falling prices not matched by falling costs, customers qualifying second sources, and margins drifting away from upstream chokepoint suppliers.
Hon Hai's declining DuPont returns illustrate the risk. Two HPQC portfolio companies show different ways to sidestep it:
SpiNNcloud competes on event-driven, energy-proportional compute rather than taking on Nvidia and AMD on FLOPS per dollar.
Q-CTRL's hardware-agnostic software doesn't depend on which qubit modality wins.
Cultivate financially healthy partners for capital, customers and exit.
Strong partners tend to invest in, co-develop with, or acquire chokepoint holders rather than build the capability themselves. The portfolio has several examples of this, both commercial and on the cap table:
Diraq's manufacturing relationship with imec, and investment from imec.xpand.
Salience Labs' volume-production partnership with Tower Semiconductor.
Mixx Technologies’ moving operations to Taiwan, with TDK Ventures and Kaynes on its register.
Q-CTRL's syndicate of strategics, including Airbus, Lockheed Martin, NTT and Salesforce.
Click here for the article.
Around the traps
“It’s not what you said, it’s the way you said it”
Leaving the short-term P&L focus to the analysts, we have been looking at some of the questions raised by recent corporate transcripts and financials.
The central theme is the growing complexity of the financing relationships developing around AI infrastructure. In summary:
Lots of contradictions in the vendor financing AI situation – either AI labs are running double or triple digit ROICs and are fantastic businesses, or they need equity capital, pushed out payables and off-take agreements. Hard to see both being true here.
All companies are pushing “guidance” further out, which suggests they have a great deal of certainty about near- and mid-term demand.
The comments around photonics and scale up optics are very exciting for that part of the stack.
Nvidia:
One of the more stark contradictions in recent Nvidia commentary concerns the financial position of the frontier AI labs.
Jensen Huang, Nvidia CEO, says repeatedly that frontier labs generate "profitable tokens," have fantastic margins, and are limited only by compute; that he heard ROIC on a $50bn data centre is less than a year.

On the very same call, Nvidia CFO Colette Kress says the same labs are growing faster than their balance sheets and credit profiles can support, and lack the investment-grade capacity to secure infrastructure on their own.
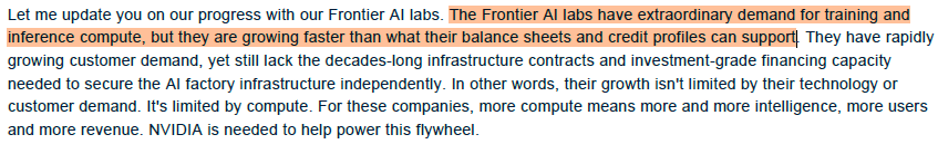
So which is it? Both can't be fully true. If payback on a $50B data centre were really under a year, as Huang says he "heard the other day," the labs wouldn't need Nvidia to provide equity, credit enhancement and take-or-pay floors.
Nvidia is taking on a lot of balance-sheet exposure.
The total was never given.
Here is the full list: roughly $50B of equity in frontier labs; credit enhancement on about 2GW for an unnamed lab; take-or-pay minimum revenue guarantees to NeoClouds, with a share of rental revenue above the floor; the SoftBank Energy land/power/shell commitment for OpenAI; and the $500B+ third-party financing platforms with Apollo, Blackstone, KKR and others.
CFO Colette Kress said balance-sheet-supported lab demand will be roughly a quarter of next year's business.
One analyst added up the commitments to about $500B and asked directly for the total and the FY28 cash component. Huang answered a different question, about custom silicon. Kress pivoted to supply commitments. Neither number was given.
The pre-emptive circular-financing defence is slightly unusual.
Companies rarely name a critique in prepared remarks unless it's hurting them. The wording was also a bit loose. "We're not making loans" sits next to take-or-pay guarantees and credit enhancement, which are contingent liabilities by another name. The take-or-pay floor means Nvidia absorbs utilisation risk. That partly undercuts its claim to be a neutral partner that doesn't own a cloud. It is effectively underwriting the clouds' downside.

Working capital is stretching.
DSO rose to 60 days on extended payment terms for large multi-quarter purchases, and inventory reached ~$32B. Each has a reasonable explanation - the Rubin launch and investment-grade buyers – but combined with vendor financing, this is a pattern that should be watched.
The phrase "investment-grade customers or those backed by one" is doing a lot of work when Nvidia itself can be considered a backer . . .
Jensen’s tone was a bit off.
There were some striking moments in Huang’s commentary.
He joked that people's stock prices double after he has dinner with them, which is a strange thing to say on a regulated call. He also called AGI milestones "senseless," while saying "we could say we've already achieved AGI." And he claimed most AI "crossed" to agentic AI "this last month," which is pretty hard to verify.

Public market commentary is a double-edged sword - and the internet never forgets!
Broadcom: another view of custom silicon
Broadcom’s recent comments directly contradict Huang's framing of custom chips.
Jensen Huang dismissed XPUs as inference chips for one cloud and said he was "100% confident" the labs would run on Nvidia long-term. Broadcom's claims point the other way.
Which is it?
Hock Tan, Broadcom CEO, described TPU 8i as "in performance it is comparable if not surpasses the Vera Rubin GPU."

On Jalapeno, OpenAI’s first custom AI inference processor developed in conjunction with Broadcom, Tan said: "And you can do all this at half the cost of a GPU."
Tan also said: "Anthropic is on track to become our largest XPU customer in 2027 and sustain that in 2028.”
The financing structure is larger than "modest" suggests.
Broadcom has a lab-financing vehicle similar to Nvidia's. Again, which is it? Strong profitability of the AI labs, and yet they are not self funding?
Broadcom CFO Amie Thuener said: "We closed the first $35 billion tranche in June for Anthropic's 1 gigawatt deployment"

Tan said: "Every gigawatt of compute they deploy, they could achieve $30 billion of ARR, annual revenue, per gigawatt."
That would represent an exceptionally large revenue opportunity, yet both suppliers say these labs need vendor-arranged financing.

Marvel: a different model again
This runs the opposite way to Nvidia's and Broadcom's financing.
Nvidia and Broadcom put their balance sheets behind customers. Marvell has given a customer equity in Marvell itself - Google.
Matt Murphy, Marvel CEO, stated: "The 8-K we filed last week, disclosing an expanded commercial agreement and associated warrant with a key hyperscaler, one of the largest adopters of custom silicon."
Murphy also said: "This one's a little unique because of the warrant that given the magnitude and the equity side, we needed to disclose it."
Scale-up optics is the fastest-moving part, and the technology choice is still open.
One of the areas we are watching particularly closely is scale-up optics. Matt Murphy's comments suggest that the technology choice remains open, making this particularly relevant to photonics and to companies operating further up the stack.

Marvell is also prepaying suppliers. This is the supply-chain version of what Nvidia calls supply commitments, and a sign of where upstream bargaining power sits. Dan Durn – new CFO:

He noted operating cash flow dipped as a result:

What we're watching
Across these results and commentary, the common thread is that the AI infrastructure stack is becoming increasingly interconnected – technologically, commercially and financially.
For investors in compute infrastructure, understanding where the physical chokepoints sit is only part of the equation. The relationships between suppliers, customers, financing partners and strategic investors may be equally important in determining how value moves through the stack.
That is where we will continue to focus our attention.


Matthew Gould Oliver Campbell
Portfolio Manager of the ICM HPQC Fund Investment Principal
MAS Licensed Representative MAS Licensed Representative
ICM Global Funds Pte Ltd ICM Global Funds
Important Note:
The information in this article should not be considered an offer or solicitation to deal in the ICM HPQC Fund (Registration number T22VC0112B SF003) or ICM HPQC Fund 2 (Registration number T22VC0112B SF007) (the “Sub-funds”). The information is provided on a general basis for informational purposes only and is not to be relied upon as investment, legal, tax, or other advice. It does not take into account the investment objectives, financial situation, or particular needs of any specific investor. Investors should seek relevant professional advice before making any investment decision. The information presented has been obtained from sources believed to be reliable, but no representation or warranty is given or may be implied that it is accurate or complete. The Investment Manager reserves the right to amend the information contained herein at any time, without notice. Investments in the Sub-funds are subject to investment risks, including the possible loss of the principal amount invested. All forms of investments carry risks, including the risk of losing all of the invested amount. Investors should read the prospectus before deciding whether to acquire the units in the Sub-funds. The value of investments and the income derived therefrom may fall or rise. Past performance is not indicative of future performance. This document is intended solely for institutional investors and accredited investors as defined under the Securities and Futures Act 2001 of Singapore. The whole or any part of this work may not be reproduced, copied or transmitted or any of its contents disclosed to third parties without ICM Global Fund’s express written consent. This advertisement or publication has not been reviewed by the Monetary Authority of Singapore.
ICM HPQC Fund and ICM HPQC Fund 2 are registered Sub-Funds of the ICMGF VCC (the VCC), a variable capital company incorporated in the Republic of Singapore. The assets and liabilities of ICM HPQC Fund and ICM HPQC Fund 2 are segregated from other Sub-Funds of the VCC, in accordance with Section 29 of the VCC Act.
Get to know us better:



Comments